
Insights on tax, equity, and building wealth
Guides and analysis from the Harness team and the advisors on the platform.
When Should an LLC Become an S-Corp? The $80K Rule Explained
If you’re running a profitable LLC, you’ve probably heard whispers—or full-on pitches—about switching to an S-Corp for tax savings. Maybe from a CPA. Maybe from TikTok. Maybe both.
The Pros & Cons of a SEP IRA vs Solo 401(k) in 2025
As self-employment has continued to grow as a career path, so too has the importance of retirement planning. The decision between a SEP IRA or Solo 401(k) carries more weight now than ever, with 2025 bringing adjusted contribution limits and fresh tax considerations.
Tax Advisor Weekly — September 26, 2025
Tax policy and client planning are intersecting more sharply than ever this week. Retirees are watching the projected Social Security COLA for 2026, while the IRS is set to phase out paper refund checks beginning September 30. Homeowners racing to claim energy-efficiency tax credits may lose their window before year-end. Meanwhile, inflation data will test whether last week’s Fed rate cut was justified. And for service workers, new clarity emerged on how “cash tips” will be treated under the tip‑tax deduction rules.
Evergreen Private Equity Funds and How They Differ From Traditional PE Structures
The long-standing dominance of fixed-term private equity funds is being challenged by evergreen funds that are reshaping PE with an open-ended structure that allows investors to enter and exit on a regular basis. Approximately $700 billion now flows through these semi-liquid vehicles, with the 5% of AUM currently allocated to evergreen funds expected to rise to 20% in the coming decade.
10 Rules for Superfunding a 529 Plan in 2025
A 529 college savings plan is a tax-advantaged tool that helps families meet the challenge of college costs. For those with substantial assets, a strategy that can be more impactful is "superfunding." Superfunding uses a special provision in the tax code to contribute a large lump sum to a 529 plan, treating it as five years of gifts. This strategy allows individuals with larger sums of money to accelerate college savings while reducing their taxable estate.
Tax Advisor Weekly — September 19, 2025
As tax enforcement tightens and generational wealth divides widen, advisors are being pulled in every direction. Gen X clients are struggling to build lasting financial legacies, just as the IRS ramps up pressure on digital asset payrolls and cash-heavy small businesses. Meanwhile, a little-known strategy is helping retirees earn up to $141K in tax-free income—if they play their cards right. In corporate tax, a high-stakes battle is unfolding as the IRS challenges common shareholder loan structures, blurring the line between debt and equity.
Harness Named to the Inc. 5000 List of America’s Fastest-Growing Private Companies for Second Straight Year
Inc. Magazine ranked Harness 192 out of 5000 companies in August 2024 and 1390 out of 5000 companies on August 12, 2025. The most recent ranking is based on revenue growth from 2021 - 2024. All companies pay a fee to be considered by Inc. for the Inc. 5000 ranking.
What is a Step Up in Basis?
Among the tax provisions relevant to intergenerational wealth transfer, "Step-Up in Basis" holds a prime position. Resetting an asset's tax basis to its fair market value upon the original owner’s death, the provision potentially eliminates capital gains taxes on appreciation that occurred during the owner's lifetime.
Tax Advisor Weekly — September 12, 2025
As new rules from Trump’s “Big Beautiful Bill” take shape, the IRS has begun previewing major changes to the 2026 W-2 and W-4 forms, including new codes for tip and overtime deductions. At the same time, legal and economic clouds are gathering: the Supreme Court has agreed to fast-track a decision on the legality of Trump’s sweeping tariffs, which could trigger billions in taxpayer refunds. And fresh revisions from the Bureau of Labor Statistics reveal that nearly 1 million jobs were overcounted earlier this year—adding urgency to calls for monetary easing.
73% of Clients Say Trust Is the #1 Priority. Here’s How to Build It Before the First Meeting
According to a recent Harness survey, nearly three-quarters of high-income clients place trust above all other factors when choosing a tax advisor. Not expertise. Not pricing. Trust.
Flagship Report: What High-Income Clients Want from Their Tax Advisors in 2025
Whether it's the opportunity to provide higher value services or gain the benefits of a long-term professional relationship, it's not difficult to understand what tax advisors are looking for in high-income clients. What high-income clients are looking for in a tax advisor, however, is a little more complicated.
IRA Recharacterization Deadline 2025 – Rules, October 15 Cut-Off & How-To Guide
IRA recharacterization is a mechanism that allows you to switch between traditional and Roth IRAs when your circumstances change. It's essentially an "undo" button for a contribution, letting you move money from a Roth IRA to a traditional IRA, or vice versa, as if the original contribution never happened.
Angel Investing Guide: How to Start in 2025
Angel investing has evolved. Once reserved for venture insiders, early-stage investing is now more accessible to individuals looking to diversify their portfolio and get closer to innovation. In 2025, new tax advantages, stronger protections, and a surge in high-growth startups make it a compelling time to explore this asset class.
Tax Advisor Weekly — September 5, 2025
As fiscal and monetary policy collide, tax professionals are working through uncertainty from all angles. The Fed is signaling rate cuts as early as this month, while Trump’s most sweeping tariffs have just been ruled unlawful by a federal appeals court. Meanwhile, the Treasury has released its list of jobs eligible for the new tip tax exemption—and yes, influencers made the cut. Over in global logistics, China’s shippers are reorienting to avoid upcoming U.S. port fees.
Liquidity Events and the NIIT Tax Rate: How to Manage the 3.8% Surtax
The Net Investment Income Tax (NIIT) is a 3.8% surtax applied to certain investment income for individuals, estates, and trusts whose Modified Adjusted Gross Income (MAGI) exceeds specific threshold amounts. Part of the Health Care and Education Reconciliation Act of 2010, NIIT was a revenue-generating measure designed to support healthcare reform by taxing investment income as opposed to labour income.
Consumer Interest Tax Deductibility in 2025: What You Can and Can't Deduct
Understanding consumer tax deductibility has never been simple—and 2025 has added a new wrinkle. Thanks to recent updates in the tax code, certain Americans can now deduct interest paid on personal-use vehicle loans. It’s a notable shift from long-standing rules that excluded most consumer interest, and it opens the door for more strategic tax planning.
How the $1000 'Trump Accounts' for Kids Will Work
Starting in 2025, a new tax-advantaged savings vehicle is being introduced for families: Trump Accounts for Kids. These federally backed accounts provide $1,000 in seed funding for eligible newborns, with tax-deferred growth and contribution opportunities designed to support long-term wealth building.
Tax Advisor Weekly — August 29, 2025
The Trump administration’s tax and trade policies remain front and center this week, as new battles over digital regulations escalate and economic inequities sharpen. Trump is threatening tariffs against countries targeting U.S. tech companies, while a new study shows billionaires pay significantly lower effective tax rates than most Americans. Meanwhile, Social Security’s COLA bump for 2026 may not be enough to keep pace with inflation, and Republicans are scrambling to rebrand Trump’s unpopular “One Big Beautiful Bill.”
Contribution Margin on an Income Statement
Every business has expenses. But not all costs—and not all dollars earned—are created the same. If you're looking to get more strategic about pricing or simply running leaner in 2025, understanding your contribution margin on an income statement is one of the smartest places to start.
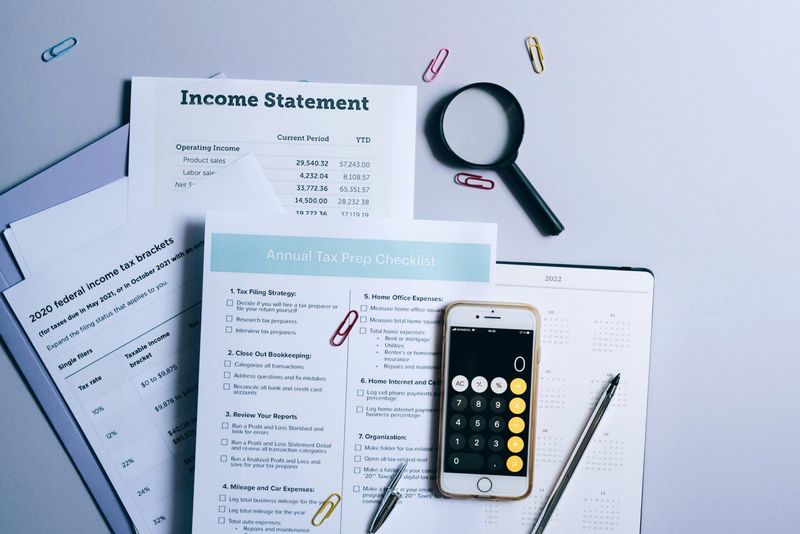
2025 Tax Brackets: A Guide to New Income Thresholds & Deductions
The IRS has released its official inflation-adjusted 2025 tax brackets, and the implications for taxpayers go well beyond just a few thousand dollars in threshold shifts. With the recent passage of the One Big Beautiful Bill, many provisions from the 2017 Tax Cuts and Jobs Act (TCJA) have now been made permanent—including the seven-bracket structure and a higher standard deduction.
How the One Big Beautiful Bill Impacts Venture Tech
President Trump's "One Big Beautiful Bill Act" (OBBB) of 2025 materially changed multiple tax and policy provisions with a direct impact on tech startups and investors. This article examines how these changes impact everything from tax benefits to international partnerships, and provides strategies for tech companies to thrive amid new compliance requirements.
How the One Big Beautiful Bill Impacts Startups and Founders
On July 4, 2025, the tax laws impacting America's entrepreneurs shifted with the signing of the "One Big Beautiful Bill" (OBBB) Act. This comprehensive tax reform package rewrites the rules of business ownership and investment, creating a new set of tax laws for businesses of all sizes.
13 Essential Small Business Tax Deductions for 2025
Running a small business means keeping a lot of plates spinning—from hiring and operations to marketing, client work, and cash flow. But when tax season rolls around, all that hustle can either help or hurt you—depending on how well you’ve planned for deductions.
Tax Advisor Weekly — August 22, 2025
The ripple effects of Trump’s tax and tariff policies are accelerating. S&P Global just reaffirmed the U.S. credit rating—but only because rising tariff revenues are plugging holes left by sweeping tax cuts. Meanwhile, the IRS may delay the 2026 tax season due to ongoing staff cuts and logistical backlogs. And a new actuarial forecast shows Social Security cuts are approaching even faster than previously expected.
Get the newsletter
Tax and equity insights, delivered to your inbox.